
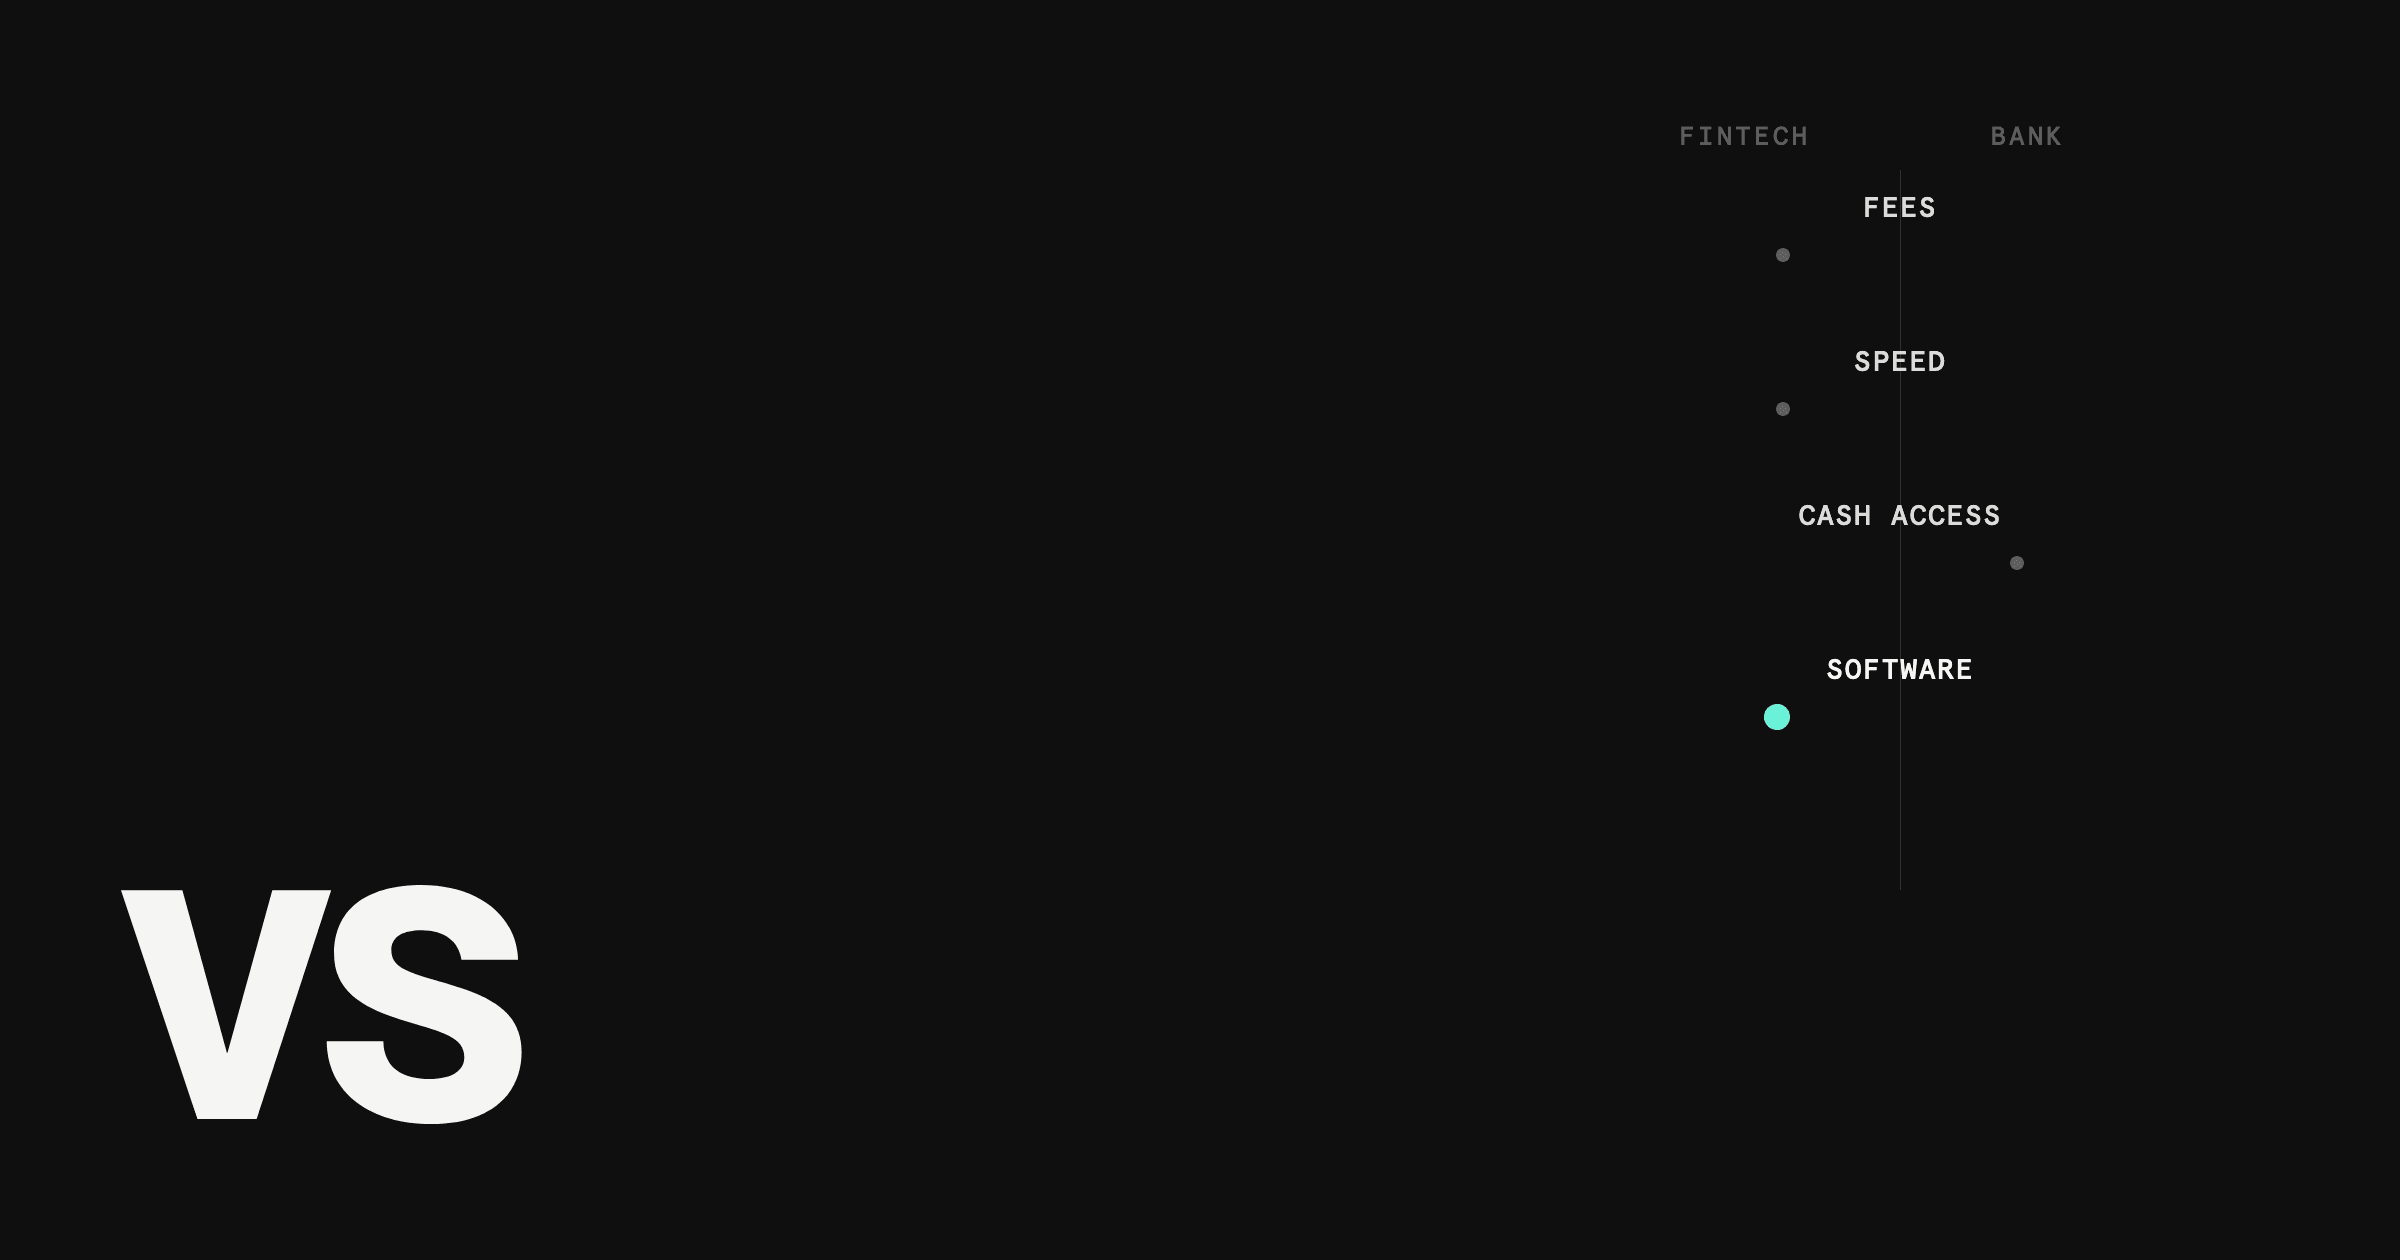
The online banking vs. traditional banking question isn't about which one is objectively better. It's about which fits how a specific business actually operates.
A fintech banking platform is usually cheaper and faster to open, with more built-in software for running the business day to day. A traditional bank is usually better if the business handles a lot of physical cash, needs a branch and a banker for lending conversations, or wants a single institution that holds its own bank charter.
Most businesses land clearly on one side once they weigh four factors:
Fees
Speed to open
Cash and branch access
How much day-to-day financial software is included versus bolted on
Here's how the two actually differ, what each real business gets and gives up, and a straight decision framework for which one fits.
What 'fintech banking platform' actually means
A fintech banking platform is a technology company that builds the account, the card, the dashboard, and the software layer on top of banking, but doesn't hold a bank charter itself. The actual FDIC-insured deposit account sits at a chartered partner bank behind the scenes. The fintech is the product and the brand; the bank is the regulated custodian of the money.
This is true across nearly every company in this category. Mercury describes itself in its own disclosures as "a fintech company, not an FDIC-insured bank," with banking services provided through Choice Financial Group and Column N.A. Bluevine's site carries nearly identical language: "Bluevine is a financial technology company, not a bank," with deposits FDIC-insured through Coastal Community Bank and its program banks.
Rho, this piece's working example throughout, is structured the same way: a fintech company whose checking and card services are provided by a chartered partner bank, not by Rho itself (see the full disclosure at the bottom of this page).
So what does that structure actually mean for the business banking there?
That structure is why fintech accounts can move fast and ship software quickly: they're not running a bank's core infrastructure, compliance stack, and branch network themselves. It's also why the "is my money safe" question comes up so often.
It's usually a non-issue as long as the partner-bank relationship is disclosed and the FDIC coverage is real, which is worth checking directly on any fintech's own site before opening an account. Rho, for instance, publishes FDIC coverage of $250,000 per entity, not per account, through its partner bank, a concrete, checkable detail rather than a vague assurance.
What a traditional bank is, by contrast
A traditional bank like Chase or M&T Bank holds its own banking charter, is itself the FDIC-insured institution, and runs its own branch network, tellers, and lending desks. Chase, for example, advertises "access to more than 14,000 ATMs and 5,000 branches," and M&T positions its business accounts around "the personal touch of a community bank with the power of a wide network."
Nothing about the account is white-labeled from a separate tech company; the bank is the bank.
The tradeoff is pace and software. Traditional banks weren't built as software companies, and it shows in account-opening friction, thinner built-in tooling, and more manual paperwork for anything beyond a basic checking account.
The real tradeoffs
Fees
Traditional bank business checking is usually a monthly fee that gets waived if the business keeps a minimum balance or hits a spend threshold. Fintech platforms mostly compete on having no such fee to waive in the first place.
Provider | Tier | Monthly fee | Waived by |
|---|---|---|---|
Chase | Business Complete Banking | $15 | $2,000 minimum daily balance, QuickAccept deposits, or Chase Business credit card spend |
Chase | Performance Business Checking | $40 | $35,000 combined average balance |
Chase | Platinum Business Checking | $95 | $100,000 average balance (or $50,000 if linked to a Private Client account) |
M&T Bank | Business Essential Checking | $5 | Waived first 3 months, then via $1,000 average ledger balance or $300/month in card purchases |
Mercury | Free tier | $0 | No minimum balance required |
Bluevine | Standard | $0 | No minimum required (yield-bearing tiers add a monthly cost) |
Relay | Starter | $0 | No minimum required |
Relay | Grow | $30 | Not waivable |
Relay | Scale | $120 | Not waivable |
Rho | All plans | $0 | No subscription fees, no per-user fees, no platform fees (banking, corporate cards, expense management, Bill Pay) |
Fees and waiver thresholds as of September 2026.
The pattern holds across the board: traditional banks charge unless you clear a balance or spend hurdle, up to $95/month at Chase's Platinum tier or $5/month at M&T; fintechs, including Rho, mostly don't charge at all.
Speed to open an account
This is the point where the "fintech is just faster" narrative needs a real caveat rather than a blanket claim. M&T now advertises a "100% digital application, no paperwork required" for its Essential tier, opening in under 10 minutes online, though that fast path is limited to sole proprietors; other entity types still need a branch visit or an appointment.
Rho publishes an account-opening time of less than 10 minutes. The honest read is that fast digital onboarding is no longer exclusive to fintechs; it's exclusive to whichever bank or platform built the software for it, and increasingly some traditional banks have.
Where fintechs still pull ahead is consistency across entity types. A fintech's fast online path typically works the same way whether the business is a sole proprietorship, an LLC, or a C-corp, where several traditional banks still route anything past a sole prop to a branch appointment.
Cash handling and branch access
This is the clearest place traditional banks win outright.
Chase Business Complete Banking: $5,000 in free cash deposits per statement cycle
Chase Performance Business Checking: $20,000 per statement cycle
Chase Platinum Business Checking: $25,000 per statement cycle (fees apply above each threshold)
M&T Business Essential Checking: $2,500 per month in cash deposited or supplied before additional fees apply
A business that handles daily cash, retail or restaurant receipts, needs this kind of built-in, branch-based capacity.
Fintechs are not uniformly locked out of cash entirely, though. Relay supports cash deposits through the Allpoint+ network (free up to $1,000 per transaction, same-day before 3 p.m. ET) and through Green Dot at more than 90,000 retail locations, with a fee up to $4.95 and per-transaction caps between $500 and $1,500 depending on the retailer (as of September 2026). It's a real capability, just built on a retail network rather than a branch network, and at lower per-transaction ceilings than a bank teller.
Feature depth
This is where fintech platforms typically pull ahead, because the software is the product rather than an add-on.
Native accounting integrations: NetSuite, QuickBooks Online, Sage Intacct, and Puzzle, plus bank-feed connections to Xero and QuickBooks Online
Free expense management, with no user or platform usage fees
Free Bill Pay
Free invoicing for all customers (pay-by-card invoices carry a 2.9% + $0.30 fee, absorbed by the business, not billed as a platform fee)
Traditional banks generally don't build this layer themselves. A business banking with Chase or M&T that wants integrated expense management, bill pay, or invoicing is usually stitching in a separate piece of software on top of the account, at its own separate cost.
Lending relationships
Traditional banks still have the edge for anything that depends on an in-person underwriting relationship: SBA loans, commercial real estate financing, or a line of credit sized to a long banking history. That's a genuine, durable reason a business with real borrowing needs keeps a traditional bank relationship even if it also uses a fintech platform for day-to-day operations.
Which type of business is actually better served by each
Choose a traditional bank if:
The business handles meaningful physical cash on a regular basis
It needs in-person deposit or lending conversations
It's a non-sole-prop entity that still needs a branch visit to open an account anywhere convenient
Chase and M&T both fit this profile well, with the caveat that fees only disappear once the business clears a minimum-balance or spend threshold. See our list of the best banks for startups for a deeper look at this side of the decision.
Choose a fintech platform if:
The business is digital-first and doesn't handle significant cash
It wants the account, the card, and the operating software (accounting sync, expense management, bill pay, invoicing) in one place with no monthly fee to manage
This is the profile Rho, Mercury, and Bluevine are all built for.
Use both if:
The business has real cash flow through a fintech platform day to day but also needs an active lending relationship or occasional branch service
Plenty of businesses keep a traditional bank account open specifically for that, while running operations through a fintech platform. Nothing about a fintech account structurally prevents also holding a traditional bank account elsewhere. Our roundup of the best online business bank accounts covers more of the hybrid options.
If Rho sounds like the fit for the fintech side of that decision, see how the platform works.
FAQs
Neither is universally better. A fintech platform is typically better for a digital-first business that wants low fees and built-in software; a traditional bank is typically better for a business with heavy cash handling or complex lending needs. The right answer depends on which of those two profiles the business actually matches.
Not entirely, and not soon. Fintechs have taken real share in digital-first small business banking, but traditional banks still hold structural advantages in cash handling, branch-based lending, and serving businesses that want everything under one chartered institution. The more likely outcome is continued coexistence, with many businesses using both.
It depends on the business's cash handling and software needs more than its size. A cash-heavy retail or restaurant business is usually better served by a traditional bank with a strong branch network; a digital-first service or software business is usually better served by a fintech platform with free integrated tools.
An LLC can open an account with either a fintech platform or a traditional bank; the entity type itself doesn't dictate the choice. What matters more is whether the LLC needs branch access and lending relationships (lean traditional) or free integrated software and no monthly fees (lean fintech).
Safety depends on FDIC coverage and the strength of the partner-bank relationship, not on whether the account is opened online or in a branch. A fintech account with clear, published FDIC coverage is not inherently less safe than a traditional bank account.