
Reconcile weekly or daily, not monthly. Small batches clear quickly, and errors surface while people still remember the purchase.
Code at the swipe. A charge that arrives with a category, a cardholder, and a receipt takes a fraction of the time to match.
Fix exceptions, not everything. Review only the charges that break a rule, and let the rest post.
Corporate card reconciliation is the work of matching every card charge to a receipt, a coding decision, and a ledger entry. Finance teams do it faster by reconciling continuously instead of at month-end, coding charges when they happen, and chasing receipts the same week.
The slow part is rarely the matching itself. It is the waiting: for a late feed, a missing receipt, a manager who has not approved. This guide shows where the time goes and how to take it out.
How do finance teams reconcile corporate card spend faster?
Finance teams reconcile corporate card spend faster by reconciling continuously instead of at month-end: pull charges into the ledger as they post, capture receipts and coding at purchase, auto-code routine spend, and review only exceptions. The result is a month-end that confirms the books instead of building them.
If you need the basics first, our guide to credit card reconciliation covers the definition and the standard steps. This guide picks up where that one stops and focuses on speed.
Steps to reconcile corporate card spend faster
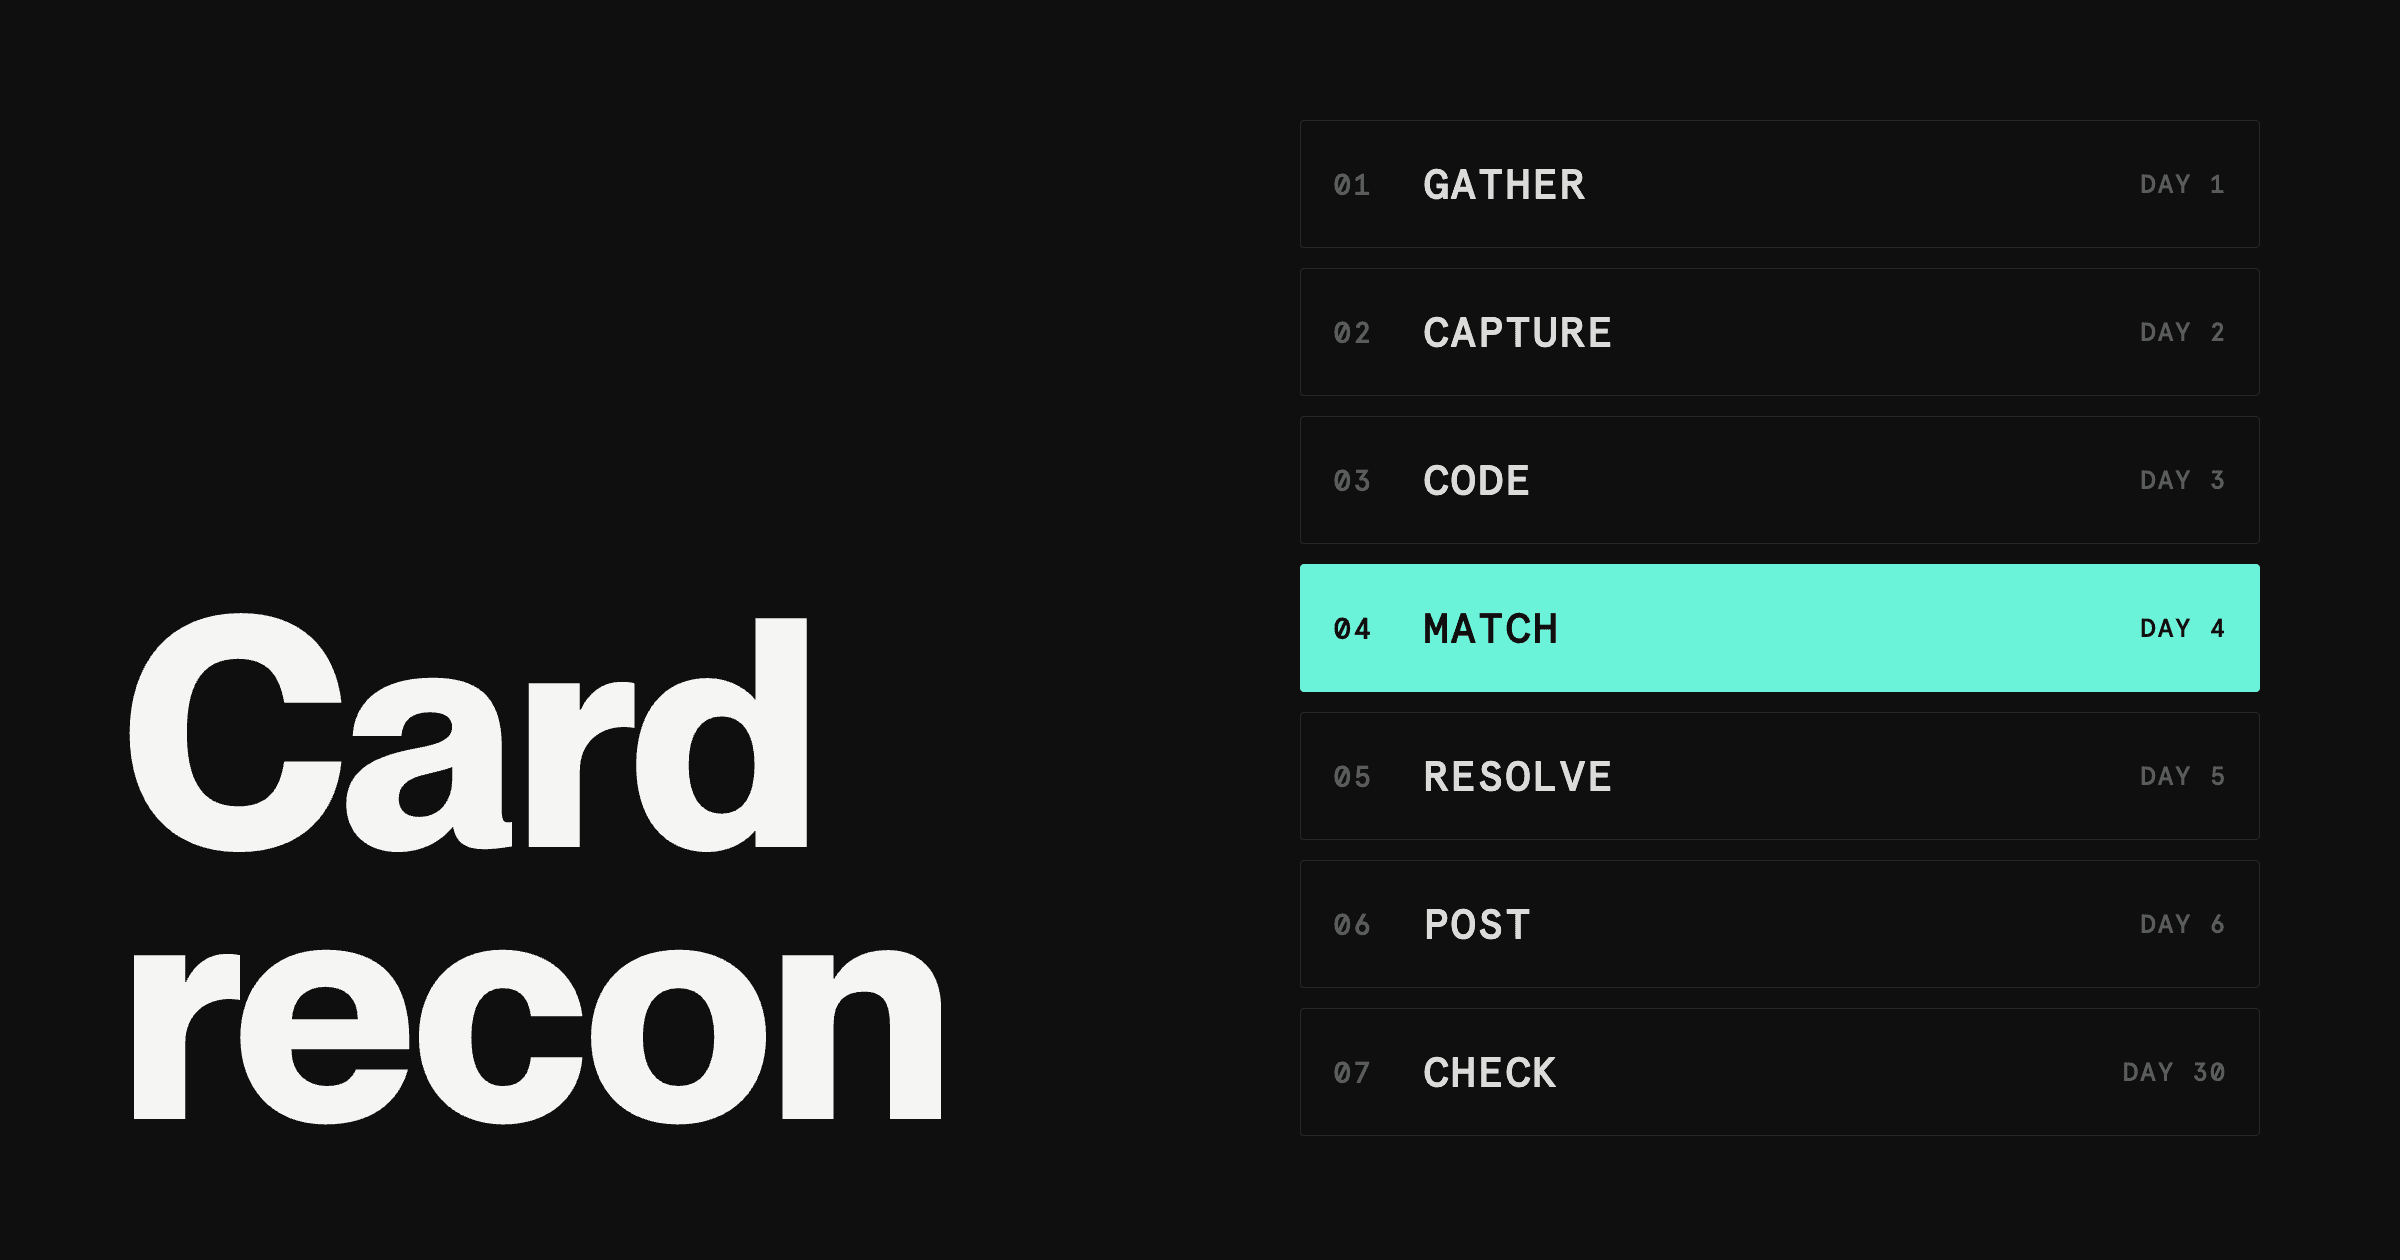
Most finance teams run some version of the same cycle: gather, capture, code, match, resolve, post, check. Speed comes from how you set up each stage.
1. Get card transactions into one place continuously
Waiting for the monthly statement means every other step waits too. Pull transactions from the card program as they post, through a feed or an integration, so you are working from live data.
Start with a single source of truth. If charges live in a statement PDF, an expense tool, and a spreadsheet, you will spend the first hour of every close deciding which one is right.
2. Capture receipts and context at the point of purchase
Receipt chasing is the biggest single drag on close. The fix is to collect the receipt, the business purpose, and the cardholder's note when the charge happens, not three weeks later when nobody remembers it.
Mobile capture helps. A cardholder who snaps the receipt at the counter creates a record that takes seconds to match. One who digs through email at month-end creates a ticket.
3. Code charges with rules, not by hand
Map recurring merchants and card types to general ledger accounts once. A software subscription, a travel booking, and a contractor payment each have an obvious home, so a saved rule should place them there without a person touching them.
Review the rules quarterly. Rules that drift are a quiet source of misclassified spend.
4. Match transactions to receipts and approvals daily
Matching a day of charges takes minutes. Matching a month takes much longer, and the odds of a duplicate or a miscoded charge hiding in the pile go up with the volume.
Set a short rhythm: Monday for the prior week, or a daily sweep if volume is high. The point is that nothing sits long enough to become a mystery.
5. Resolve exceptions fast, by type
Sort what does not match into named buckets: missing receipt, duplicate charge, personal purchase, vendor billing error, wrong category, late approval. Each bucket has a standard resolution and a standard owner. When the exception has a name, it has a next step.
Send reminders on a schedule, not on a whim. A missing-receipt nudge on day two works better than a month-end blast.
6. Post to the ledger and clear the card liability
Once charges are matched and coded, post them to the general ledger and record the card payment against the liability. Do this on the same rhythm as matching so the balance you see in the ledger is the balance the card issuer shows.
7. Check the statement last, as a control
At month-end, compare the ledger total to the issuer's statement. If you reconciled all month, this is a two-minute check that confirms the work. If the numbers differ, you have a short list of days to look at, not a month to re-do.
Each of these seven steps gets easier when the card program hands you clean data. The comparison below shows the difference.
Manual vs automated corporate card reconciliation
Automation removes retyping, waiting, and re-checking, so judgment goes to the charges that need it.
Task | Manual | Automated | Why it matters |
|---|---|---|---|
Getting transactions | Download statement, copy into a spreadsheet | Feed or integration posts charges to the ledger | No retyping, fewer transcription errors |
Receipts | Email requests, month-end chase | Captured at purchase, attached to the charge | Removes the longest delay in the close |
Coding | Accountant assigns each charge | Saved rules apply a category; humans review exceptions | Consistent categories, less review time |
Matching | Line-by-line against the statement | Charges matched as they post | Errors surface within days, not weeks |
Month-end close | Build the picture, then check it | Confirm a picture that already exists | Faster close, calmer finance team |
Audit trail | Scattered across email and spreadsheets | One record per charge | Easier to answer an auditor's question |
Read the table row by row, not as a verdict. A small team with 30 charges a month may do fine with a spreadsheet. The gap opens as volume and card count grow.
The published numbers point the same direction. Corpay's reconciliation guide cites Aberdeen research putting a manually processed expense report at $20.65 against $6.85 automated, and cites Levvel Research data, in an Aberdeen Group report, finding 74% of companies still rely on manual processes for invoice and expense reconciliation (Corpay's page was updated June 17, 2026).
In a February 2026 post, Navan, citing a Forrester study it commissioned, reports 8 hours a week saved and 80% less time per expense report. These are vendor-published figures, so treat them as directional, not as a benchmark for your team.
Common causes of slow reconciliation
If your close drags, the cause is usually one of these. Find yours before buying anything.
Delayed or incomplete feeds. Charges arrive late or in batches, so matching starts late. Check how often your card program sends data to your ledger.
Missing receipts. The charge is real, the proof is not. This is the most common source of exceptions and the one most worth fixing at the source.
Late approvals. A charge sits unreviewed because the approver is traveling or the queue is long. Agree on a turnaround window and a backup approver.
Billing-cycle overlap. A charge made on the 30th posts on the 2nd, so it lands in a different period than the receipt. Decide in advance how to handle cut-off dates.
Manual posting to the ledger. Rekeying data takes time and introduces errors. Every manual step is a place to lose a day.
Fragmented systems. Cards in one tool, expenses in another, the ledger in a third. Each handoff is a delay and a chance for the data to disagree.
None of these is about the accountant's skill. All of them are about when and how the data arrives.
What to look for in a corporate card if reconciliation is the goal
The card you choose sets the starting quality of your data. If reconciliation is a pain point, check for these:
Native accounting integration with the ledger you use, not just a CSV export. Ask which systems are native and which are bank feeds.
Receipt capture on mobile, so the cardholder can attach proof at the point of purchase.
Coding at the transaction level, so charges can carry an accounting category before they reach you.
Spending limits and spend controls that stop out-of-policy charges before they become exceptions.
Virtual and physical cards with clear cardholder attribution, so every charge has an owner.
Expense tooling pricing that does not scale with headcount, so adding cardholders does not add cost to your close.
A clear eligibility fit, so you know the card is available to your business before you build a process around it.
For a broader side-by-side of providers, see our guide to the best corporate cards and our overview of corporate credit card expense management software.
Where Rho fits
Rho is a business banking and corporate card platform. The Rho Card with Daily Terms earns up to 1.25% Cashback on card spend (terms apply), and up to 2% Cashback with Rho Platinum on Daily Terms (terms apply), on up to $1M in eligible annual card spend.
On the reconciliation side, Rho has native integrations with NetSuite, QuickBooks Online, Sage Intacct, and Puzzle, and supports bank feed connections to Xero and QuickBooks Online.
The Rho mobile app lets cardholders upload receipts with OCR, code transactions to accounting categories, and handle expense approval. Team and vendor cards can be created and managed with card controls from the Rho mobile app. There are no per-user fees on Rho expense management.
Rho is available to US-incorporated businesses only. Sole proprietors and unincorporated businesses are not eligible.
If your team spends close week chasing receipts and rekeying charges, start with a card that lets cardholders attach receipts and code charges from their phone, and that connects natively to your ledger. See how the Rho Card works and who it is available to. Explore the Rho Card.
Keep reading
FAQs
Corporate card reconciliation is matching each charge on a corporate card statement to a receipt, a coding decision, and a ledger entry. Its purpose is to confirm that every charge is accurate, authorized, and recorded correctly. It also catches fraud, duplicates, and personal purchases before they reach the books.
They reconcile continuously instead of monthly, capture receipts and coding at the time of purchase, apply saved coding rules, and review only exceptions. Pulling card transactions into the ledger as they post removes the biggest delays, which are waiting on feeds and chasing receipts.
Monthly is the minimum, because the issuer's statement closes monthly and your ledger liability should agree with it. Most teams that close fast also match charges weekly or daily during the month, then use the statement as a final check.
Create the entry when a charge is matched, coded, and approved, and record the card payment against the liability when you pay the statement. If you post charges as they clear review, the month-end entry becomes a check, not a rebuild.
The best fit depends on your ledger, card volume, and how much of the process you want automated. Look for a direct feed from the card program, receipt capture, rule-based coding, and a native connection to your accounting system. Compare options against those four before comparing price.
A spreadsheet with columns for date, merchant, amount, cardholder, category, receipt status, and match status is enough for a small program. It stops scaling when charges run into the hundreds a month, because every column becomes manual work.
Rho cards are available to US-incorporated businesses. Sole proprietors and unincorporated businesses are not eligible.
Yes. Rho has native integrations with NetSuite, QuickBooks Online, Sage Intacct, and Puzzle, and supports bank feed connections to Xero and QuickBooks Online.
Missing receipts, late or incomplete feeds, billing-cycle overlap, late approvals, and manual posting. Most are timing problems rather than accuracy problems, which is why moving receipt capture and coding earlier fixes them.